
Your static caravan or lodge is much more than somewhere to stay. It’s your home from home, a place to switch off, enjoy holidays and spend time with family and friends.

So, whether you own a static caravan or holiday lodge, it’s important to make sure it has the right protection.
But what does static caravan and lodge insurance actually cover? How much should you insure your caravan for? What happens if you let friends and family use it? And what should you do if you need to make a claim?
In this video, our Claims Liaison Manager, Steph, answers some of the questions we’re regularly asked about insuring a static caravan or lodge.
Why choose specialist holiday caravan insurance?
Holiday caravans have specific insurance needs that can be different to those associated with your main home.
Specialist holiday caravan insurance can protect your static caravan or lodge against unexpected events such as storms, floods, fires, theft and accidental damage, as well as providing other benefits designed specifically with holiday caravan owners in mind.
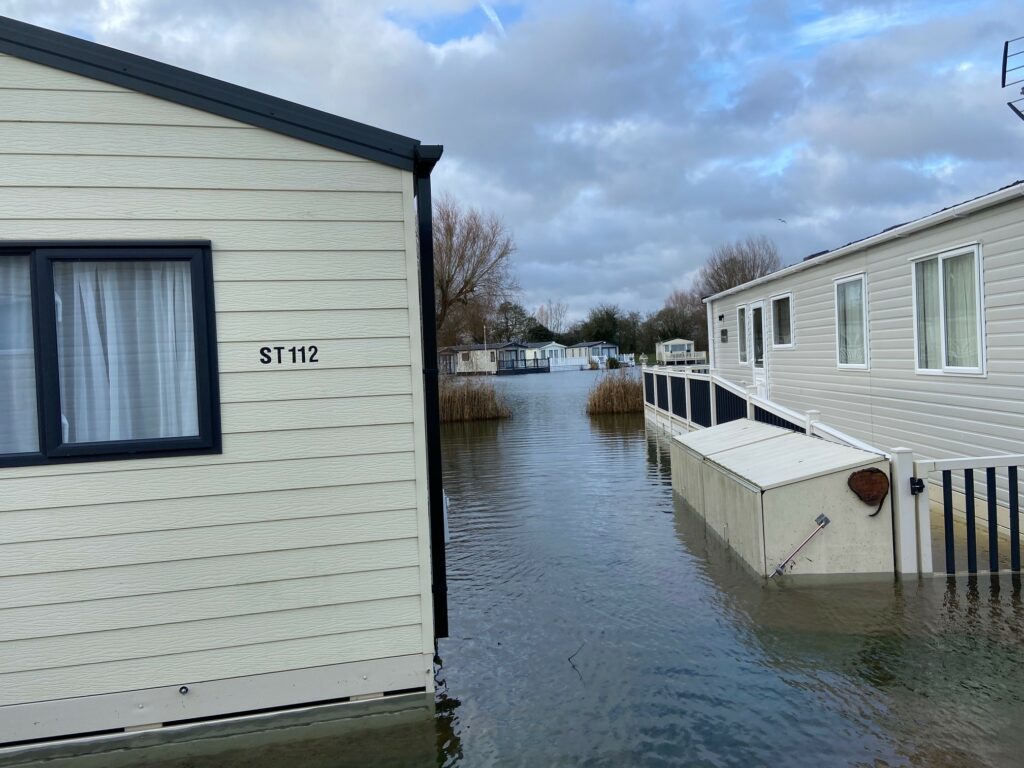
Depending on the policy, specialist cover can include things such as:
– Emergency accommodation
– Emergency repair costs
– Debris removal and resiting
– Reimbursement of ground rent following damage
– Public liability
– Cover for contents and personal possessions
Before choosing a policy, it’s worth looking carefully at the cover provided rather than focusing solely on price. You could also check independent review websites such as Trustpilot and Smart Money People to see what existing customers say about the static caravan insurance provider.
What information do you need for a holiday caravan insurance quote?
When getting an insurance quote for your static caravan or holiday lodge, it helps to have some key information to hand.
This might include:
– The make and model of your caravan or lodge
– Length and width
– Number of bedrooms
– How the caravan is constructed
– Whether it’s anchored
– The holiday park name, address and postcode
– Your plot number
– The replacement value of the static caravan or lodge on your current park
– The value of fixtures and fittings, such as decking and sheds
– The value of the contents you keep inside
Getting these values right is important. Remember to account for all the contents you keep at your holiday caravan, including TV’s, smart speakers, appliances such as kettles and toasters, pots, pans, crockery and bedding, as well as items kept in sheds or outdoor storage.
Your holiday park might be able to help you establish the current value of your caravan and the cost of a new or like-for-like replacement.
Market value or new for old cover
When arranging holiday caravan insurance with Leisuredays, cover might be available on either a market value or new for old basis. So, what’s the difference?
Market value cover
Market value cover means insuring your holiday caravan and its fixtures and fittings, along with your contents, for their current value.
For the caravan itself, you should consider what it would cost to replace it with one of the same age and condition, sited on your holiday park at the time of a claim.
New for old cover
New for old cover means insuring your holiday caravan and contents for the cost of replacing them with brand new equivalents.
When working out the value of your static caravan or lodge, it’s important to consider the price the park would charge to provide a brand new unit to your pitch.
Whichever type of cover you have, review your sums insured regularly to make sure they remain sufficient.
Are the contents of your holiday caravan insured?
Contents and personal possessions can also be covered as part of your holiday caravan insurance.
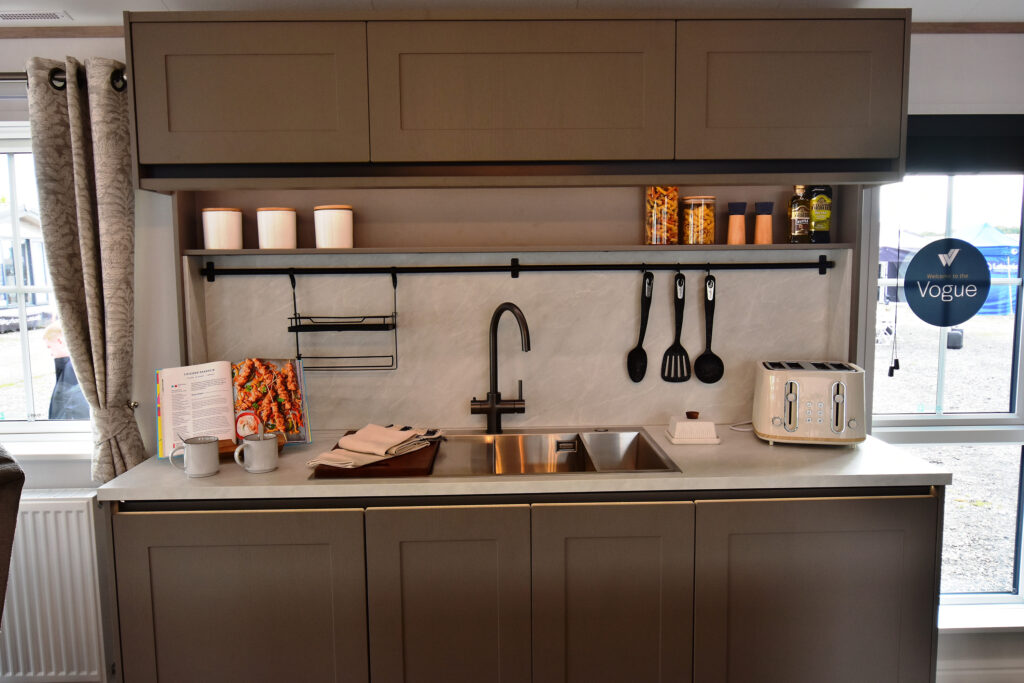
Think about everything you keep in your caravan, from pots, pans and bedding to appliances and furnishings. Keeping an up-to-date inventory and taking photographs can make it much easier to work out how much cover you need and provide useful information should you ever have to make a claim. Also, in terms of personal belongings such as clothing, consider how much of these you take on an average holiday in your caravan. Of course, personal belongings can often be covered away from home on a standard household insurance policy, so it’s worth checking if you already have that cover at home before duplicating cover on your caravan insurance.
Some higher-risk belongings, such as mobile phones, laptops and jewellery, might not be covered by your holiday caravan insurance. Again, check whether these are insured whilst away from home under your home insurance policy.
Can friends and family use your static caravan?
With a Leisuredays policy, friends and family can use your holiday caravan as you would, provided they’re not paying to stay.

If you’re planning to hire your caravan out to other holidaymakers for financial reward, you’ll need to make sure hiring-out cover is included on your policy. You should also check that your holiday park allows you to hire out your caravan.
What changes should you tell your insurer about?
Don’t assume that you only need to speak to your insurer when your policy is due for renewal.
Let them know if something changes that could affect your insurance. For example:
– You change your home address
– You replace your static caravan or lodge
– You add decking, a hot tub or other insured fixtures
It’s also important to review the sum insured at each renewal. Replacement costs and market values can change, so check that the figure on your policy remains appropriate.
Keeping your insurer updated helps make sure your policy accurately reflects your circumstances if you ever need to make a claim.
What are some common static caravan insurance claims?
Static caravans and lodges can be exposed to everything from harsh winter weather to accidental mishaps.
Some of the common static caravan insurance claims our team handles include storm and flood damage, burst pipes, accidental damage, vermin damage and fire.

Although not every incident can be prevented, there are steps you can take to reduce some of these risks.
Storm damage
Before bad weather arrives, secure or bring inside loose items such as garden furniture. Keeping gutters clear and checking the seams and seals around your caravan can also help keep it protected from the elements.
Burst pipes and escape of water
During cold weather, water left inside pipes can freeze and cause considerable damage.
A condition of Leisuredays cover is to drain down your caravan’s water system between November 1st and March 15th when you’re leaving it unoccupied overnight.
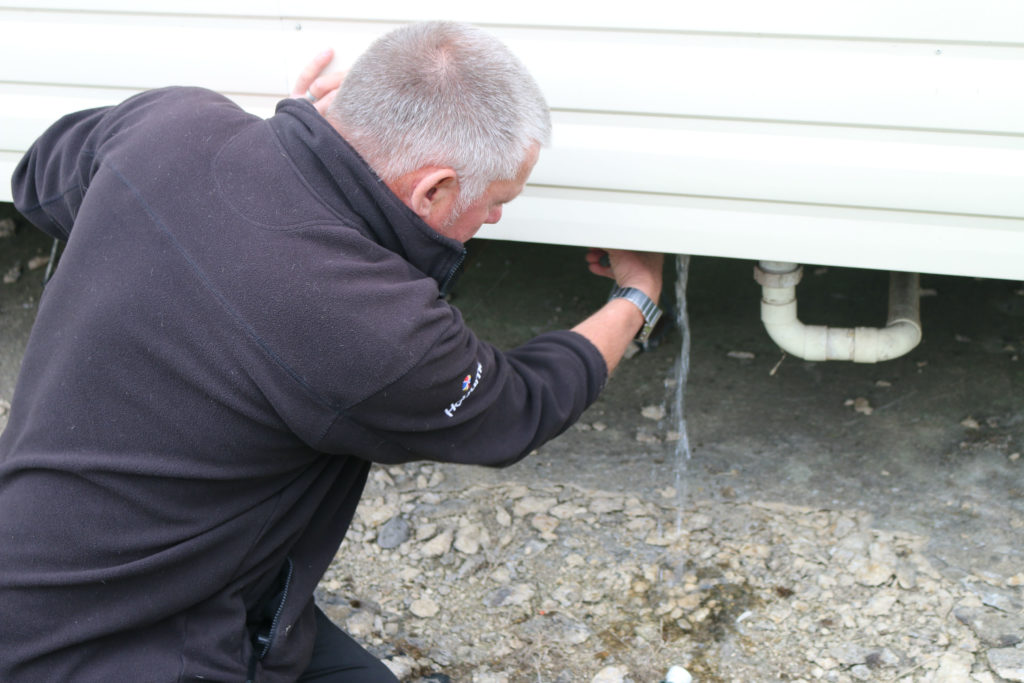
You can drain down the system yourself or ask your holiday park for help.
Accidental damage
Cracked shower trays, damaged carpets and broken windows are just some of the accidental damage claims that can happen in a holiday caravan.
Simple precautions can make a difference. For example, using a bath or shower mat can help reduce the risk of slips and trips in the shower.
Vermin
Mice and other vermin can cause extensive damage inside a holiday caravan.
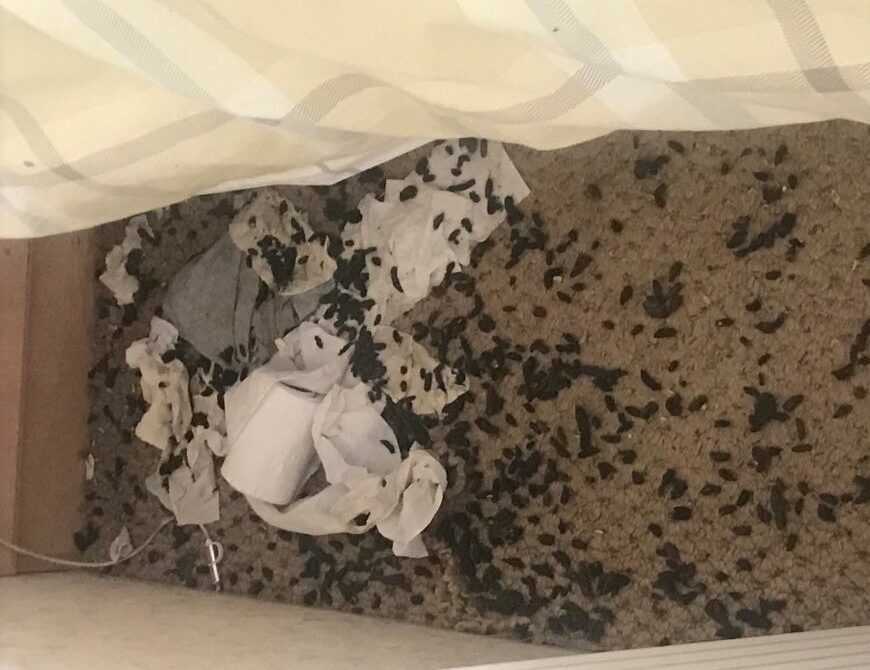
When closing up for an extended period, make sure there’s no food left behind which could attract unwanted visitors. Taking bedding home can also help.
Fire
Fire claims might be less frequent, but the damage can be devastating.

Regularly check your smoke alarms, avoid leaving devices charging overnight, and make sure barbecues are fully extinguished and positioned safely away from the caravan and decking.
What should you do if you need to make a holiday caravan insurance claim?
If your static caravan or lodge is damaged, your first priority should always be safety.
Provided it’s safe to do so:
1. Make the area safe and take reasonable steps to prevent further damage.
2. Take photographs of the damage.
3. Carry out temporary repairs if necessary to prevent further damage – but only if safe to do so. Leisuredays’ policy does include cover to make emergency repairs such as the cost of boarding a broken window up.
4. Contact your insurer to register the claim.
5. Keep evidence of the damage and any relevant costs or repair quotations.
With Leisuredays, a non-urgent claim can be registered online through the customer portal. For emergency help, you can call our claims team on 01422 501085.
Once a claim has been registered, you’ll receive a claim reference and might be asked to provide photographs and a repair estimate. For more extensive damage, a loss adjuster might need to inspect the caravan. The claim can then be assessed against your policy cover before settlement.
A little preparation can go a long way
None of us wants to think about something happening to our static caravan or holiday lodge, but having suitable insurance and taking a few preventative measures can provide valuable peace of mind.
Remember to regularly check that your sums insured are sufficient, keep a record and photographs of the possessions in your caravan, tell your insurer when circumstances change, and prepare your caravan properly when leaving it for extended periods.

Then you can spend less time worrying about what might go wrong and more time relaxing in your home from home.
For more information about Leisuredays holiday caravan and lodge insurance, take a look at our insurance information, guides, FAQs and customer reviews at www.leisuredays.co.uk.
Benefits and discounts are subject to terms and conditions, cover level and underwriting criteria. As an existing customer of Leisuredays, your schedule will confirm cover features applying to your policy.


